Multifamily Loans
Financing for apartment buildings with 5 or more units. Bridge loans are funded from our own capital. Value-add, 30-year rental, and ground-up multifamily construction programs are arranged through our lending partners*.
Maximum leverage shown. Actual leverage may be reduced based on property location, appraisal, in-place income, market conditions, borrower experience, credit, liquidity, project scope, property type and other underwriting factors. Terms subject to lender approval and program guidelines.
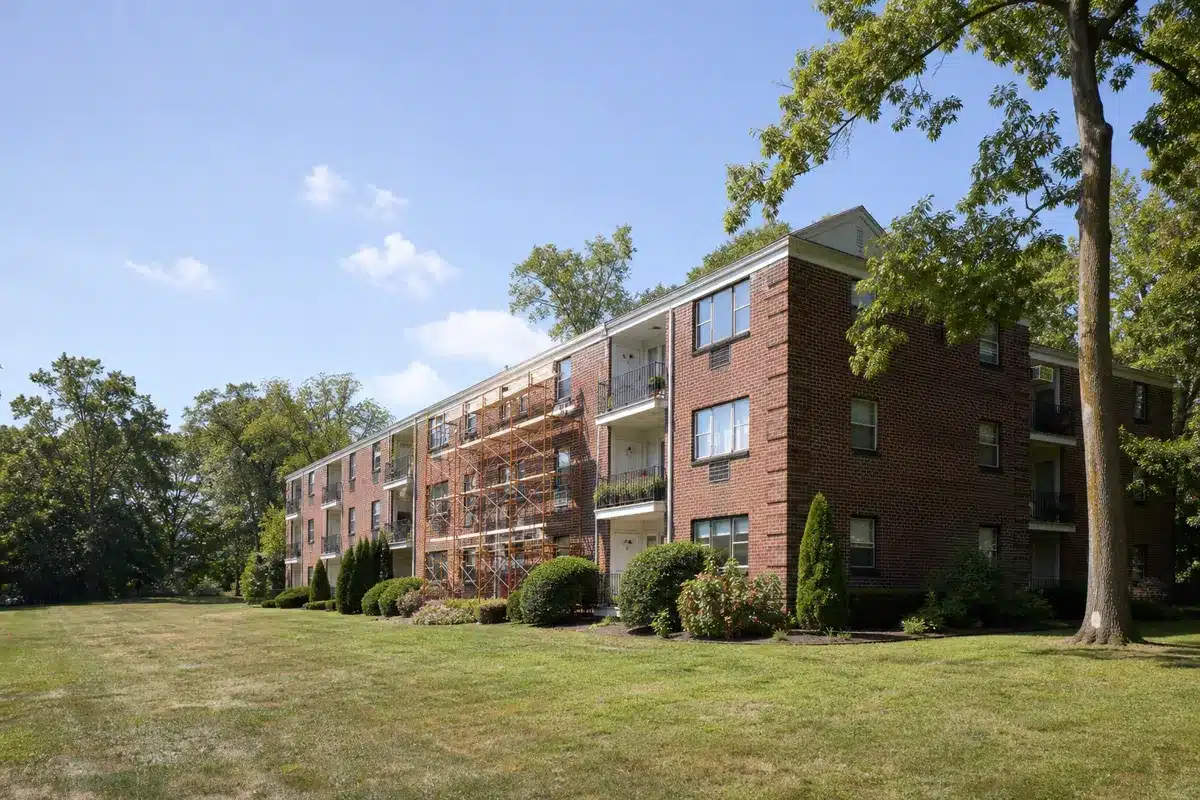
A multifamily loan finances a residential building with five or more units, such as a walk-up, a garden-style complex, or a mid-rise. Unlike a 1 to 4 unit rental, a building this size is underwritten mainly on the property itself: the rent roll, the operating expenses, the net operating income, and how much debt that income can support.
Investors use multifamily financing to buy a stabilized building, buy and renovate to raise rents, hold for the long term, or build new. Each goal calls for a different kind of loan, and we cover all four.
Best fit: an investor with a building under contract or already owned, a current rent roll and operating history, and a clear plan, whether that is holding, renovating, or refinancing into long-term debt.
Which program fits
| Buying or refinancing, short term | Bridge |
| Buying to renovate and raise rents | Value-add* |
| Holding for the long term | 30-year rental* |
| Building from the ground up | Construction* |
| Larger commercial deals | Partner lenders* |
Bridge loans are funded directly by VeeCasa Funding. Programs marked * are arranged through partner lenders. Not a quote.
From a short-term bridge to a 30-year hold.
Short-term financing funded from our own capital, to buy or refinance an apartment building while you stabilize it or line up long-term debt. Interest only, up to 65% of value. We size bridge loans conservatively, to the property’s value and in-place income, so the refinance at the end actually works.
Purchase and renovation in one short-term loan for buildings that need work: unit turns, deferred maintenance, or repositioning to raise rents. The renovation budget is released in draws as work is completed. Arranged through our lending partners.
Long-term financing for stabilized buildings, with fixed, adjustable, and interest-only options. Qualification is based mainly on the property’s cash flow. A common exit from a bridge or value-add loan. Arranged through our lending partners.
Ground-up construction of 5+ unit buildings, funded through inspected draws as the project is built. Built for experienced developers. Arranged through our lending partners.
Financing 2 to 4 units? See Fix & Flip, Renovation, or DSCR Rental*.
Send the address, unit count, purchase price or current loan, rent roll, and your plan for the building.
We tell you which program fits and whether we fund it directly or place it with a lending partner.
You get terms in writing before you commit. No hard credit pull to start.
We review the property, the income, your experience, and the exit, then close in your entity’s name.
Bridge and value-add loans are repaid on sale or by refinancing into long-term financing.
For this page, a residential building with five or more units. Properties with 2 to 4 units are financed through our fix and flip, renovation, and DSCR rental programs.
Yes, for bridge loans, which we fund from our own capital. Value-add, 30-year rental, multifamily construction, and larger commercial loans are arranged through our lending partners*. We tell you which applies before you commit.
Up to 65% of value, sized to the most conservative of the purchase price, the appraisal, and the value supported by the building’s in-place income. Final terms depend on underwriting.
Yes. Occupied buildings are common. Expect to provide a current rent roll, leases, and a trailing 12-month operating statement.
Yes. Many investors use a bridge loan to buy or stabilize a building, then refinance into a 30-year multifamily loan arranged through our partners*. Plan the refinance before you close on the bridge.
Experience is required and reviewed case by case. Experience owning or operating apartment buildings strengthens your terms, and ground-up multifamily construction is for experienced developers.
Yes. For larger commercial loans, we work with commercial bridge and construction lenders*. Tell us about the deal and we will find the right fit.
Yes. Our direct bridge loans require a minimum credit score of 650. Below 650, we may still lend when the loan is 50% of the property’s value or less. Borrowers cannot be involved in pending litigation or open liens. Partner programs set their own credit requirements.
We lend nationwide on non-owner-occupied investment property. Availability depends on the property and the program.
It depends on the loan and the program. Any prepayment terms are spelled out in your term sheet before you commit.
Send us the rent roll and your plan. We will come back with the right program and terms, or a straight answer.
Maximum leverage percentages shown are guidelines only and represent maximum potential leverage, not guaranteed loan terms. Actual leverage may be reduced based on the overall risk profile of the borrower, property, and project.
Factors that may result in lower leverage include, but are not limited to: rural or sparsely populated locations; declining or unstable property values identified by the appraisal or other market data; in-place income, occupancy, and lease terms; limited comparable sales; unique, specialized, or non-conforming properties; low marketability or liquidity; high renovation or construction costs relative to property value; borrower experience; credit profile; liquidity and reserves; project feasibility; appraisal findings; title, environmental, or property-condition concerns; and other geographic, market, collateral, or underwriting risks.
Loan amount, leverage, interest rate, fees, term, and other conditions are determined on a case-by-case basis and are subject to lender underwriting, appraisal, due diligence, program requirements, and final approval. Programs, guidelines, and terms are subject to change without notice. Not all borrowers or properties will qualify for maximum leverage.
* Value-add bridge, 30-year multifamily rental, multifamily new construction, larger commercial loans, and DSCR rental loans are arranged through partner lenders and are not funded directly by VeeCasa Funding. Terms, eligibility, and approval are set by that lender.
VeeCasa Funding LLC makes loans for business and investment purposes only, secured by non-owner-occupied real estate, to business entities only. These are commercial loans. They are not consumer mortgages, are not intended for personal, family, or household use, and are not subject to NMLS or SAFE Act licensing. Loan programs, terms, leverage, and availability are subject to underwriting, property review, and credit approval, and may change without notice. Not a commitment to lend.
VeeCasa Funding LLC · 301B Amboy Ave, Woodbridge, NJ 07095 · (732) 314-1874
VeeCasa Funding LLC · 301 Amboy Ave, Woodbridge, NJ 07095 · (732) 314-1874
Loans are for business or investment purposes only and are not available for personal, family or household use or for owner-occupied property. Loans are made to entities (LLCs and corporations). Approval is subject to underwriting, property evaluation and eligibility; terms vary by loan. *DSCR rental loans are arranged through a partner lender and are not funded directly by VeeCasa Funding.